EXCLUSIVE MILITARY ADVANTAGES
A Mortgage Benefit You Earned Through Your Service
VA home loans can provide eligible veterans, active-duty service members, and surviving spouses with flexible ways to purchase or refinance a primary residence.
$0 Down Payment
Finance up to 100% of your home purchase price with no mandatory down payment requirement for qualified buyers.
No Mortgage Insurance
Save hundreds each month with zero private mortgage insurance (PMI) premiums, unlike conventional or FHA loan alternatives.
Competitive Financing
Benefit from government-backed interest rates that are routinely lower than standard conventional loan options.
Limited Closing Costs
VA rules restrict the types and amounts of closing fees lenders can charge, protecting you from excessive out-of-pocket expenses.
Reusable Lifetime Benefit
Your VA loan entitlement is not a one-time opportunity. You can reuse your benefit throughout your life as your housing needs evolve.
Flexible Credit Guidelines
VA loan programs offer more forgiving credit benchmarks and debt-to-income allowances compared to standard conventional products.
Streamlined Refinancing (IRRRL)
Lower your monthly mortgage payment with minimal paperwork, no required appraisal, and expedited processing through the VA Interest Rate Reduction Refinance Loan (IRRRL).
Disclaimer: Not affiliated with or endorsed by the U.S. Department of Veterans Affairs or any government agency. Equal Housing Opportunity. VA loan eligibility is subject to specific military service requirements, certificate of eligibility (COE), underwriting criteria, and credit approval.
LIFETIME BENEFIT SOLUTIONS
VA Financing for Different Stages of Homeownership
Whether you are purchasing your first home, lowering your monthly payments, tapping into accrued equity, or transferring an existing low-rate loan, your earned military benefit adapts to every milestone.
VA Purchase Loan
Designed for active-duty servicemembers, veterans, and eligible surviving spouses buying a primary residence with full military entitlement benefits.
- 0% down payment required
- No private mortgage insurance (PMI)
- Competitive government-backed rates
VA IRRRL
The Interest Rate Reduction Refinance Loan (Streamline Refinance) helps homeowners with an existing VA loan quickly lock in lower interest rates.
- Minimal underwriting paperwork
- Often requires no home appraisal
- Roll closing costs into loan balance
VA Cash-Out Refinance
Access built-up home equity to consolidate high-interest debt, fund significant renovations, or switch from a conventional to a VA loan program.
- Borrow up to 90-100% home value
- Convert non-VA loans into a VA mortgage
- Cash available at loan closing
VA Loan Assumptions
Take over an existing seller's low-interest-rate VA mortgage directly, preserving favorable legacy financing terms during high-rate markets.
- Assume historically low interest rates
- Reduces buyer closing fee totals
- Entitlement substitution options
QUALIFICATION CRITERIA
Could You Be Eligible for a VA Home Loan?
VA home loans offer significant advantages including $0 down payment options, competitive interest rates, and no private mortgage insurance (PMI). You may qualify if you meet any of the service categories below:
Military Veterans who served on active duty and met minimum service requirements
Current Active-Duty Service Members with at least 90 continuous days of service
National Guard and Reserve Members with qualifying service history (typically 6+ years)
Surviving Spouses of service members who died in the line of duty or from service-connected disabilities
Cadets and Midshipmen at U.S. Military, Naval, Air Force, or Coast Guard Academies
Takes under 2 minutes • No impact on your credit score
SEPARATING FACT FROM FICTION
Common VA Loan Myths
Misconceptions keep thousands of military families from utilizing their hard-earned benefit. Here is the real truth behind financing with a VA loan.
Myth 1: VA Loans Take Significantly Longer to Close
Fact: Modern digital processing allows VA purchase loans to close in an average of 30 to 45 days, matching conventional mortgages timelines when working with an experienced military lender.
Myth 2: VA Loan Offers Aren't Competitive in Hot Housing Markets
Fact: VA-backed buyers are among the strongest in the market, backed by federal guarantees, zero down payment requirements, and statistically lower foreclosure rates than conventional borrowers.
Myth 3: You Can Only Use Your VA Loan Benefit Once in a Lifetime
Fact: Your VA loan benefit is fully reusable. You can restore your entitlement after paying off a previous loan, and can even carry multiple active VA loans simultaneously under bonus entitlement guidelines.
Myth 4: Military Service Automatically Guarantees Loan Approval
Fact: A Certificate of Eligibility (COE) establishes your military service qualification, but approved private lenders still review debt-to-income, residual income standards, and credit history to approve financing.
Myth 5: VA Loans Are Exclusively for First-Time Homebuyers
Fact: VA financing is available for first-time buyers, repeat purchasers, move-up buyers, and downsizers alike, as long as the home is purchased as your primary residence.
SENIOR MORTGAGE BROKER & VA LOAN SPECIALIST
Your Trusted Guide to VA Financing & Home Ownership
With years of dedicated experience in mortgage lending, Kurt specializes in helping military families, veterans, and first-time buyers navigate the financing landscape with clarity, speed, and confidence. Get personalized mortgage solutions engineered to secure your ideal terms.
Specialized VA Loan Programs & Zero-Down Options
Direct Broker Access & Fast-Track Approvals
Transparent Guidance from Pre-Approval to Closing
Direct broker consultation · No obligation · Transparent advice
What is your primary goal?
Step 1 of 4: Select the option that best describes your needs
Information Confirmed!
Thank you. We have received your qualifications and prepared your tailored options.
FREQUENTLY ASKED QUESTIONS
Everything You Need to Know About VA Loans & Licensing
Clear, verified answers regarding VA eligibility, funding fee structures, streamline IRRRL refinances, and regulatory lending standards.
What are the primary service and eligibility requirements for a VA home loan?
To qualify for a VA loan, borrowers must have served on active duty for at least 90 consecutive days during wartime, 181 days during peacetime, or more than six years in the National Guard or Reserves (or 90 days under Title 32 orders with at least 30 consecutive days). Eligibility is officially verified through a Certificate of Eligibility (COE) issued by the Department of Veterans Affairs based on military discharge papers (DD-214) or statement of service.
How do VA loan limits and zero-down financing work under full entitlement?
Under the Blue Water Navy Vietnam Veterans Act of 2019, veterans with full available entitlement are not subject to standard FHFA conforming loan limits. Eligible buyers can purchase a qualifying primary residence with 0% down payment regardless of loan size, provided they meet the lender's credit, debt-to-income, and residual income requirements.
What is the VA Funding Fee and how is it determined?
The VA Funding Fee is a one-time federal charge required by law that helps sustain the VA home loan program for future generations without taxpayer burden. The fee percentage varies based on military status, the down payment amount, whether it is your first or subsequent time using the benefit, and loan type (purchase, cash-out, or IRRRL streamline refinance).
Who is legally exempt from paying the VA Funding Fee?
You are exempt from paying the VA funding fee if you receive VA disability compensation for a service-connected disability, are rated eligible to receive compensation following a pre-discharge exam, are an active-duty service member who has received the Purple Heart, or are a surviving spouse eligible under specific VA statutory guidelines.
Can the VA Funding Fee be financed into the total mortgage balance?
Yes. Borrowers have the option to pay the VA funding fee in full at closing out of pocket or finance it directly into the total loan balance, allowing for true zero-out-of-pocket initial cost options on qualifying purchases and refinances.
What is a VA Interest Rate Reduction Refinance Loan (IRRRL)?
A VA IRRRL, also referred to as a VA Streamline Refinance, is a specialized refinance product designed exclusively for homeowners with an existing VA loan. It allows borrowers to refinance into a lower interest rate or shift from an adjustable-rate mortgage (ARM) to a fixed-rate mortgage with significantly reduced documentation and faster closing timelines.
Is an appraisal or income underwriting verification mandatory for a VA IRRRL?
The Department of Veterans Affairs does not mandate a full property appraisal or complete income re-verification for an IRRRL. However, individual mortgage lenders may implement internal underwriting overlays requiring basic credit checks, automated valuation models (AVMs), or employment verification.
What are the VA Net Tangible Benefit and seasoning rules for an IRRRL?
VA regulations mandate that an IRRRL must provide a distinct financial advantage to the borrower. Fixed-to-fixed refinances must reduce the combined interest rate by at least 0.50%, and all closing costs and fees must be recouped within 36 months. Additionally, the existing loan must meet strict seasoning rules: at least 210 days from the first payment date and 6 full monthly payments made.
What credit score is required to secure approval for a VA loan?
The VA does not establish a universal minimum credit score benchmark. Instead, lenders assess overall credit history and residual income. Most approved VA mortgage lenders set their automated underwriting cutoffs between 580 and 620, with options for manual underwriting on lower scores when compensating factors exist.
Is private mortgage insurance (PMI) required on VA mortgages?
No. Unlike conventional loans with less than 20% down or FHA loans with upfront and monthly Mortgage Insurance Premiums (MIP), VA home loans do not charge monthly private mortgage insurance (PMI), resulting in substantial monthly payment savings over the life of the loan.
Can a veteran use their VA loan entitlement benefit multiple times?
Yes. The VA loan is a lifetime benefit. Once an existing VA mortgage is paid off and the property is sold, full entitlement is restored. In addition, veterans may utilize remaining 'bonus entitlement' (second-tier entitlement) to purchase a subsequent primary residence while keeping their initial home as a rental under qualifying conditions.
Can surviving spouses qualify for VA mortgage benefits?
Unremarried surviving spouses of service members who died in the line of duty, from a service-connected disability, or who are missing in action (MIA) or prisoners of war (POW) may qualify for full VA home loan benefits, including 0% down payment financing and complete exemption from the VA funding fee.
What types of residential properties are eligible under VA loan guidelines?
VA loans finance 1-to-4 unit residential properties provided the veteran occupies one of the units as their primary residence. Eligible property types include single-family detached homes, VA-approved condominiums, planned unit developments (PUDs), modular homes, and qualifying manufactured housing meeting permanent foundation standards.
What are the primary occupancy requirements for a VA purchase loan?
VA purchase guidelines require the borrower to move into and occupy the subject property as their primary residence, generally within 60 calendar days of closing. Temporary duty or deployment exceptions exist, and a spouse can fulfill the occupancy requirement on behalf of an active-duty service member.
How does lender licensing and Nationwide Multistate Licensing System (NMLS) compliance protect VA borrowers?
Mortgage lenders and individual loan originators must be properly licensed and registered through the NMLS and approved by the VA as an authorized lender. Regulatory licensing mandates strict adherence to the Truth in Lending Act (TILA), Real Estate Settlement Procedures Act (RESPA), and federal consumer protection statutes, guaranteeing transparent fee disclosures and ethical lending practices.
MILITARY & VETERAN BENEFITS
You Served. Let’s Make Sure You Understand the Home Loan Benefits You Earned.
Take full advantage of $0 down payment requirements, lower interest rates, and no private mortgage insurance. Our VA loan specialists guide you through every step of claiming your rightful benefits.
✓ 100% Free Consultation • No Impact on Credit Score • VA Approved Lenders
Client Success Stories

SHOULDN'T BE COMPLICATED
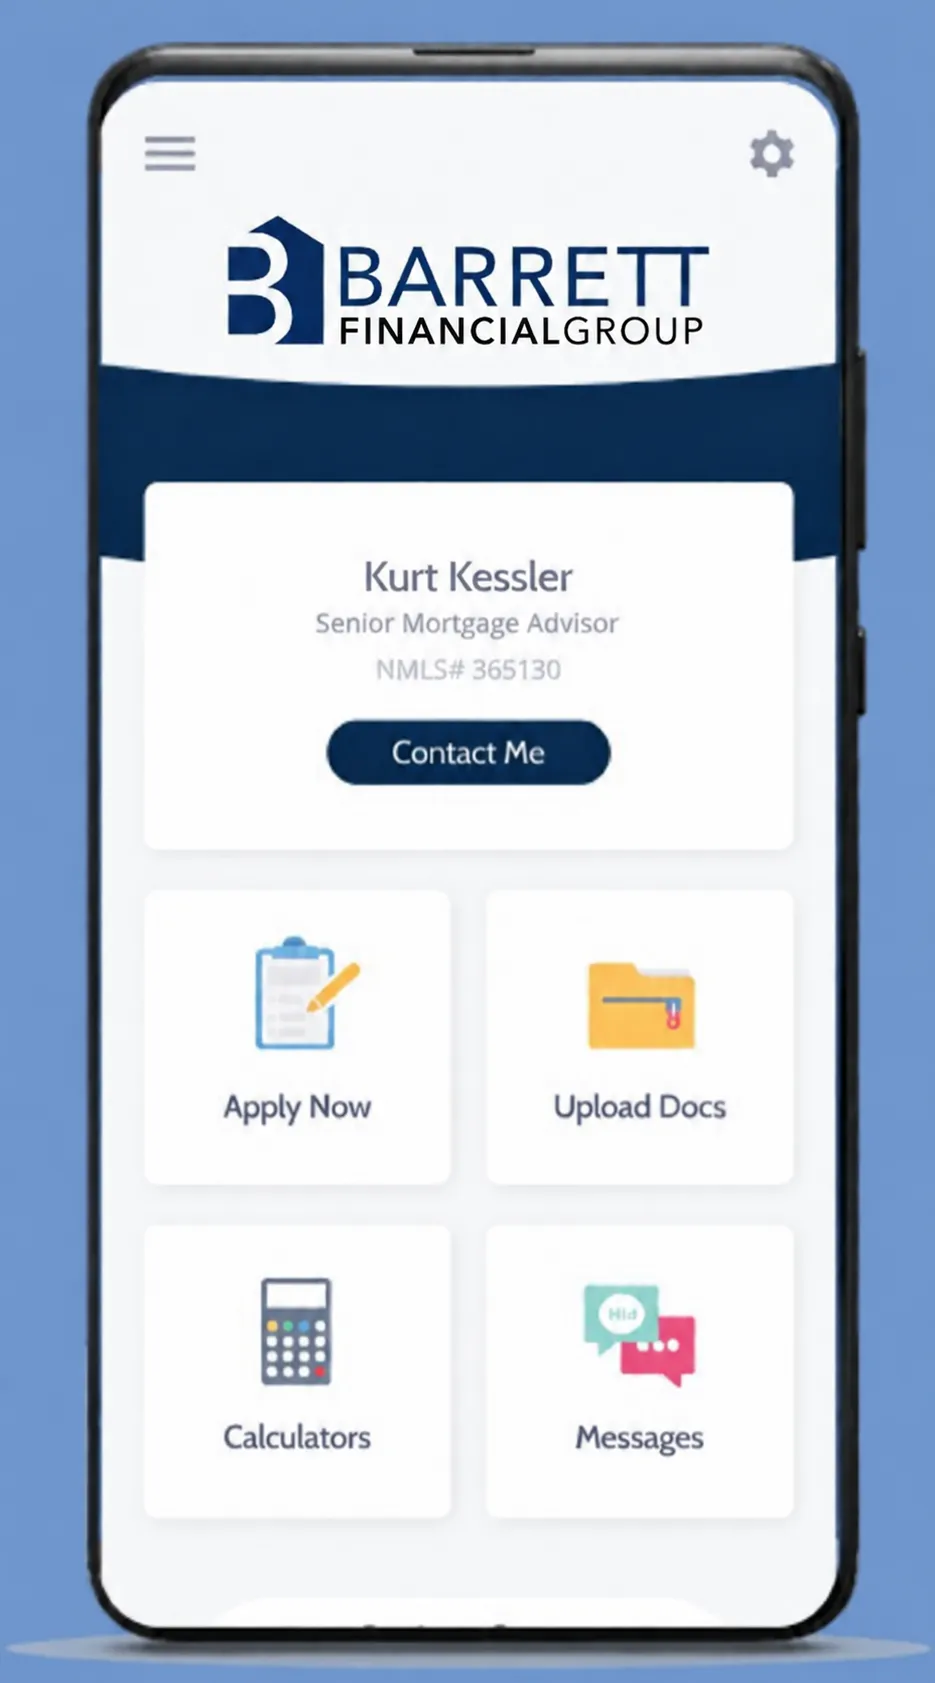
I will guide you through your mortgage financing and ensure it's a smooth process.
Apply NowBe Ready When Rates Drop
We monitor mortgage markets around the clock and alert you the second your refinance goal becomes a reality.
- Instant SMS + email alerts when rates hit your target
- Personalized to your loan balance, term, and goals
- No spam, no guesswork - just clear updates

Ready to Get Started?
Let's discuss how we can help you achieve your homeownership and wealth-building goals


 Hi there, have a question? Text us here.