UNDERSTANDING CONDO ELIGIBILITY
What Defines a Non-Warrantable Condo?
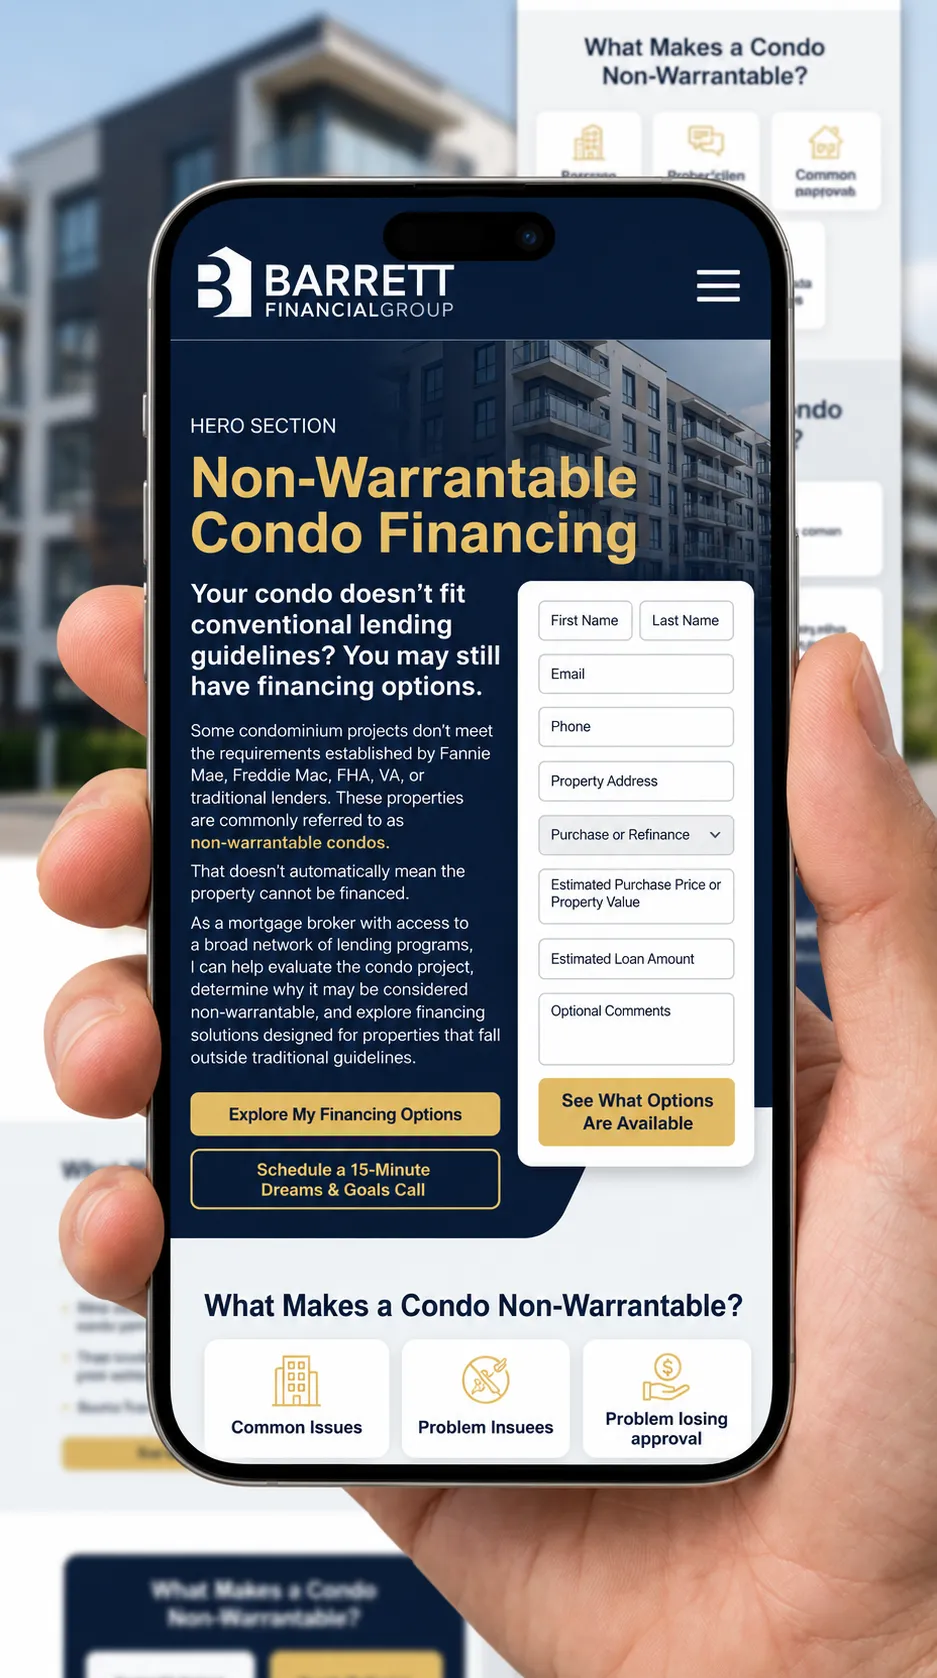
Properties that fail Fannie Mae and Freddie Mac secondary market guidelines require specialized portfolio financing. Here are the 9 core conditions that designate a condo project as non-warrantable.
High Investor Concentration
When more than 50% of the total units are non-owner occupied (investor-owned or rentals), the development exceeds conventional risk thresholds.
Single-Entity Ownership
A single person or corporate entity owning more than 10% (or 20% on smaller projects) of total units creates disproportionate financial reliance.
Commercial Space
If commercial, retail, or office allocations exceed 25% to 35% of total building square footage, agency guidelines automatically exclude the project.
HOA Financial Concerns
Insufficient reserve funding (under 10% annual budget allocation), special assessments, or >15% of owners delinquent on dues trigger red flags.
Pending Litigation
Active lawsuits involving structural defects, developer disputes, environmental hazards, or significant financial claims immediately disqualifies project review.
Insurance Issues
Inadequate master hazard, flood, or fidelity insurance, or properties located in high-risk zones facing coverage lapses cannot meet agency standards.
Short-Term Rentals
Buildings that allow daily, weekly, or vacation rentals (such as Airbnb/VRBO) without minimum lease durations are deemed transient lodging.
Condotel Characteristics
Projects featuring on-site check-in desks, mandatory rental pooling agreements, daily maid service, or hotel-like hospitality operations.
New Developments
Buildings still under construction, phases below 50-70% pre-sold/closed threshold, or where the HOA has not formally transitioned from developer control.
PROJECT REVIEW & LENDING RESCUE
Was Your Condo Loan Declined? Get a Second Look.
Most condo loan denials happen not because of your personal finances, but because standard lenders flag complex building details. Whether it's HOA reserve thresholds, ongoing litigation, investor concentrations, or deferred maintenance questionnaires, our condo desk specializes in portfolio solutions and project-level approvals.
- Non-warrantable and warranted condo solutions
- Direct review of HOA questionnaires and reserve budgets
- Financing options for pending structural or litigation concerns
- Fast turnaround to protect your earnest money and closing date
No obligation. Strict privacy. Rapid 24-hour initial feedback.
Custom Financing Available: Primary, Investment, DSCR, Non-QM & Jumbo Solutions with Fast Approvals.
PARTNER SOLUTIONS FOR REALTORS
A Non-Warrantable Condo Doesn't Always Mean a Dead Deal
Don't let rigid agency guidelines derail your transaction. We provide specialized non-warrantable condo lending solutions that keep your listings active, rescue troubled escrows, and help your buyers cross the finish line with confidence.
- Financing available for high investor ratios & single-entity ownership concentration
- Solutions for pending HOA litigation, deferred maintenance & low reserve funds
- Condotel, fractional ownership & mixed-use commercial projects accepted
- Rapid project scenario review within 24 to 48 hours to protect your escrow timeline
Fast 24-48 hr scenario turnaround • Direct access to specialist condo underwriters
OUR CORE ADVANTAGES
The Institutional Standard for Private Capital
Direct market access, seasoned insight, and custom strategies designed to preserve and grow your portfolio across market cycles.
Broker Access
Direct institutional liquidity, preferred tier execution, and access to private market opportunities without intermediaries.
Experience
Seasoned market professionals who have successfully steered client capital through every major macroeconomic cycle.
Strategy First
Custom portfolio blueprints built around your specific risk tolerance, liquidity needs, and tax-efficient growth targets.
Personal Service
Direct access to your senior portfolio strategist with transparent reporting, proactive reviews, and zero call centers.
PROJECT APPROVAL CHECKLIST
Required Documentation for Expedited Condo Review
To guarantee smooth warrantability determination and loan approval, please supply the following standard condominium verification records:
- Completed HOA / Condo Project Questionnaire (Full or Limited Review)
- Current Operating Budget, Reserve Study & Minimum 10% Reserve Allocation
- Master Insurance Policy Certificate (Hazard, General Liability & Fidelity / Crime)
- Recorded HOA Bylaws, CC&Rs & Any Active Special Assessment Disclosures
- Past 6 Months HOA Board Meeting Minutes & Litigation Status Letter
Average review turnaround is 24 to 48 business hours upon receipt of full documentation.
OUR PROVEN METHODOLOGY
Four Steps to Your Ideal Financing Strategy
A clear, structured roadmap designed to identify challenges, match optimal programs, and deliver tailored capital solutions.
STEP 01
Property Info
Submit your core property details, historical performance, and valuation baseline to kick off the review.
STEP 02
Identify Issue
Pinpoint equity gaps, title hurdles, or restrictive debt structures impacting qualification.
STEP 03
Explore Programs
Compare private, bridge, institutional, and government-backed lending programs side-by-side.
STEP 04
Financing Strategy
Execute a customized capital structure with clear amortization, competitive terms, and dedicated guidance.
Confidential consultation · No credit check required to explore options
LENDING GUIDELINES & ANSWERS
Non-Warrantable Condo Financing FAQ
Clear guidance on qualifying, HOA reviews, down payments, and closing timelines for complexes outside conventional secondary market standards.
What specifically makes a condo project non-warrantable?
A condominium is classified as non-warrantable when it does not meet Fannie Mae or Freddie Mac conventional agency guidelines. Common triggers include: a single entity or investor owning more than 10% to 20% of total units, commercial or non-residential space exceeding 35% of total square footage, pending litigation against the HOA or builder, insufficient budget allocations to capital reserves (under 10%), or heavy short-term rental/condotel usage.
Can I obtain a competitive mortgage on a non-warrantable condo?
Yes. While major secondary-market agencies will not buy these loans, specialty portfolio lenders and private banking programs actively underwrite non-warrantable condos. Borrowers can access fixed-rate, adjustable-rate, and interest-only structures with competitive rates tailored to the project's specific risk profile.
What are the standard down payment and credit requirements?
Down payment thresholds typically start at 10% to 15% for primary residences with strong borrower profiles. Second homes and investment purchases generally require 20% to 25% down. Minimum credit scores usually range between 660 and 680, though 720+ unlocks the most favorable pricing tiers.
How does pending litigation affect financing approval?
Pending litigation does not guarantee an automatic denial. Our specialized underwriters review the formal complaint, legal briefs, and association counsel response. If the litigation concerns minor construction defects, slip-and-fall claims fully covered by insurance, or disputes with limited financial exposure to reserves, the project can still be cleared for lending.
What documentation is required from the Homeowners Association (HOA)?
Approval requires a completed condo questionnaire (full or limited scope), the current operating budget reflecting reserve allocations, the latest balance sheet, the master insurance declaration page with fidelity/crime coverage, and HOA meeting minutes covering the previous 12 months.
What is the typical turnaround timeline for loan closing?
Because the HOA review and questionnaire analysis occur in parallel with borrower credit underwriting, most non-warrantable condo transactions close smoothly in 21 to 30 business days once all association documentation is received.
TAKE THE NEXT STEP
Ready to Unlock Your Ideal Condo Financing?
Get clear, tailored insights for your specific property scenario or discuss your long-term goals with our dedicated advisory team.
Price & Advice
According to Zillow, 81% of homeowners between 18 and 34 years old have at least one regret about buying their home.
Choosing a mortgage based solely on interest rate, without factoring in your broader financial plan, can limit your long-term wealth.
You deserve to own your home and build wealth. We'll help you do both.
Kurt Kessler
NMLS #365130
Client Success Stories
GETTING YOUR HOME LOAN
SHOULDN'T BE COMPLICATED
I will guide you through your mortgage financing and ensure it’s a smooth process.
Home Report
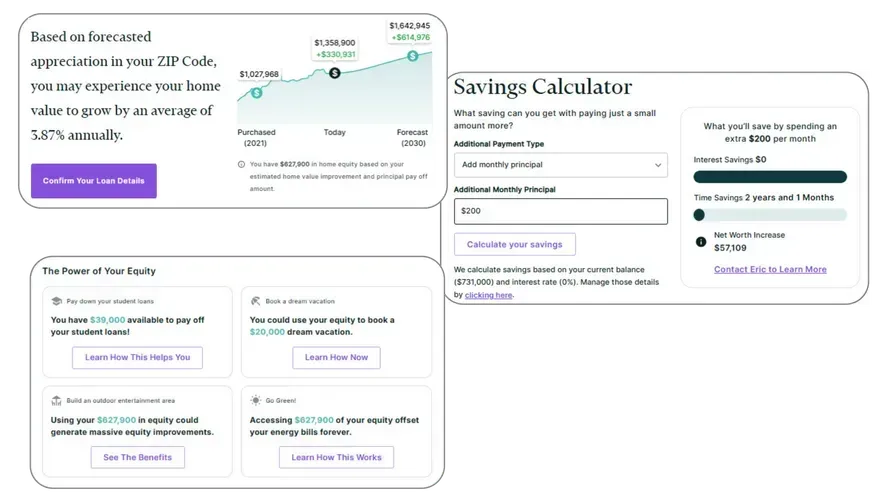
Stay informed about the value of your home!
Our free monthly report offers monthly equity statement, an intuitive financial dashboard, tailored to enhance your wealth-building journey with your most significant asset: your home.
We are committed to ensuring you always have a clear and accurate understanding of your home's value and its impact on your family's financial wellbeing.
Be Ready When Rates Drop
Monitor mortgage markets around the clock and receive alerts the second your refinance goal becomes a reality.
- Instant SMS + email alerts when rates hit your target
- Personalized to your loan balance, term, and goals
- No spam, no guesswork - just clear updates
Kurt's Calculators
8 Mortgage Calculators
- Payment Calculator
- Buydown Calculator
- Blended Rate Calculator
- Prepay or Invest Calculator
- Extra Payment Calculator
- Payoff or Save Calculator
- Target Payoff Calculator
Kurt's Buydown Guide
Buy Smarter. Lower Payments. More Options
- Compare Temporary vs. Permanent Mortgage Rate Buydowns
- See How a 2-1, 3-2-1, 1-1 or 1-0 Buydown Can Lower Early Payments
- Compare a Seller-Paid Buydown vs. a Price Reduction
- Calculate the Seller Concession Needed to Fund a Buydown
- See the Buyer’s Payment Savings by Year
- Run Real-Time Scenarios at KurtsBuydownGuide.com
Mortgage Blog
Mortgage Rates Cross 7%: What Does That Mean for You?
Mortgage Rates Cross 7%: What Does That Mean for You? ...more
Mortgage Market Insights ,DSCR Home Ownership First Time Home Buyer VA Home Loans Real Estate Market Self Employed Home Loans RealtorS Concord, CA Real Estate Martinez, CA Real Estate Market Update Antioch, CA Real Estate Market Update Buydowns Sacramento Real Estate Market &Solano County Real Estate Market
September 28, 2026 • 2 min read
Townhome, PUD, Condo: What's the difference and why does it matter
Townhome, PUD, Condo: What's the difference and why does it matter ...more
Home Ownership ,First Time Home Buyer FHA Loans VA Home Loans Real Estate Market RealtorS &Concord, CA Real Estate
September 25, 2026
Solano County Real Estate Market 2026 Insights
Explore the 2026 Solano County Real Estate Market: County real estate market trends and mortgage tips for home buyers. ...more
Solano County Real Estate Market
September 24, 2026 • 7 min read
Ready to Get Started?
Let's discuss how we can help you achieve your homeownership and wealth-building goals
Phone


This is not a commitment to lend. All loans are subject to credit approval. This information is not intended to be an indication of loan qualification, loan approval or commitment to lend. Other limitations may apply. No Tax Return loans products require other forms of income documentation and asset verification in lieu of tax returns. Not all applicants will qualify. Some products we offer may have a higher interest rate, more points or more fees than other products requiring more extensive or different documentation. Minimum FICO, reserve, and other requirements apply.
Kurt Raymond Kessler NMLS #365130 | 1082 Allegheny Drive, Danville CA 94526
Barrett Financial Group, L.L.C. NMLS #181106 | 2701 East Insight Way, Suite 150, Chandler, AZ 85286 | CA 60DBO-46052 & 41DBO-148702
Licensed by Dept. of Financial Protection & Innovation under the California Residential Mortgage Lending Act. Loans made or arranged pursuant to a California Financing Law License