How Much Income Do You Need to Qualify for a Mortgage?
Real Estate, Mortgage Qualification, California Home Buyers
How Much Income Do You Need to Qualify for a Mortgage?
If you are shopping for a home in California, you have probably wondered, “How much income do I actually need to qualify for a mortgage?” With home prices and living costs higher than many other states, this is a very fair question. The good news: lenders follow clear guidelines, and once you understand them, the path to approval feels much less mysterious.
What Lenders Really Look for in Terms of Income
When it comes to mortgage qualification, lenders are not just asking, “How much do you earn?” They are really asking, “Is your income stable, reliable, and sufficient to comfortably support this new payment?” That means they focus on a few friendly but firm guidelines rather than one magic number.
- Consistency: Has your income been steady for at least two years, or is there a clear story explaining any changes?
- Documentability: Can your income be verified with pay stubs, W‑2s, tax returns, or bank statements?
- Sufficiency: After your other monthly debts are paid, is there enough room left in your budget for the new mortgage payment?
Lenders call this your ability to repay. They will look at your gross monthly income (before taxes) and compare it to your monthly obligations. This is where the all-important debt-to-income ratio comes in.
Debt-to-Income Ratio Explained Simply
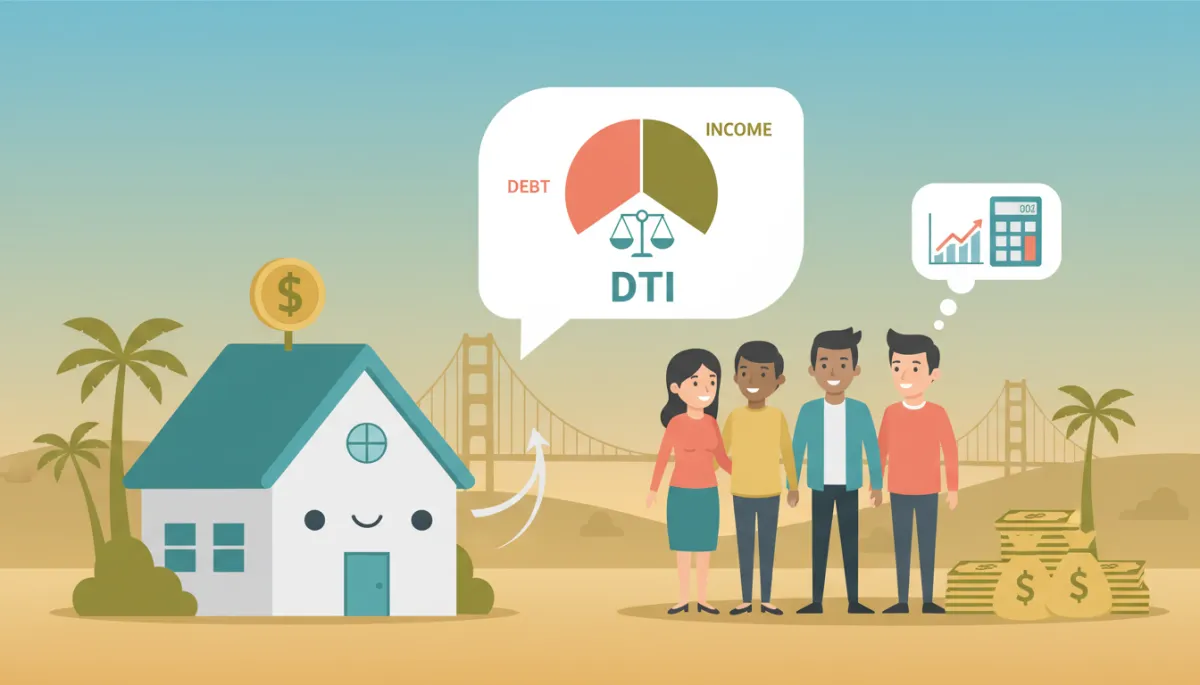
Your debt-to-income ratio (DTI) is just a comparison between what you owe each month and what you earn each month. Think of it as a quick “budget snapshot” lenders use to see whether a new payment will feel comfortable or cramped.
Here is the simple formula:
DTI = (Total Monthly Debts ÷ Gross Monthly Income) × 100
“Total monthly debts” includes things like car payments, student loans, credit card minimums, personal loans, and, of course, your future mortgage payment (principal, interest, taxes, insurance, and any HOA dues). Everyday expenses like groceries, gas, or streaming services are not counted in this ratio, even though they matter to your real‑life budget.
For many loan programs, lenders like to see a DTI at or below 43%–50%, depending on the type of loan, your credit score, and your overall profile. A lower DTI makes approval easier and may open the door to better interest rates or a higher price range. A higher DTI does not automatically mean “no,” but it does mean your file will be reviewed more carefully.
Why Income Requirements Feel Higher in California
California is an incredible place to live, but there is no denying that home prices and the overall cost of living are higher than in many parts of the country. For California home buyers, this often means you need more income to qualify for the same style of home you might find elsewhere for less.
A few factors that shape income requirements here:
- Higher purchase prices: Bigger loans mean higher monthly payments, which require higher income to keep your DTI in a healthy range.
- Property taxes and insurance: These can vary by county and neighborhood and are part of your total mortgage payment calculation.
- HOA dues and amenities: Many California communities include monthly HOA fees, which lenders add to your debts when calculating your debt-to-income ratio.
This is exactly why local guidance matters. A mortgage expert who regularly works with California buyers and real estate professionals can help you understand what price range fits your income in specific cities or counties, from the Bay Area and Sacramento to Los Angeles, Orange County, and San Diego.
Income Types That Can Help You Qualify
Many buyers assume only a traditional salary counts. In reality, lenders can work with a wide range of income sources, as long as they are stable, likely to continue, and well documented. This is especially important in California, where many people are self‑employed, work in the gig economy, or own investment properties.
- W‑2 employment income: This includes your base salary plus consistent overtime, bonuses, or commissions, typically averaged over the last two years. Lenders verify this with pay stubs, W‑2s, and an employment verification.
- Self‑employed income: If you are a freelancer, contractor, or business owner, lenders usually review two years of personal and business tax returns. They focus on your net income after expenses, not just gross revenue, so careful tax planning can make a big difference.
- Rental income: Income from rental properties can often be used to help you qualify. Lenders may count a percentage (for example, 75%) of the expected or actual rent to allow for vacancies and expenses, using lease agreements and tax returns as documentation.
- Retirement income: Social Security, pensions, and withdrawals from retirement accounts can also qualify, especially if they are expected to continue for at least three years. Statements and award letters are typically used to document this income.
- Other consistent income: In some cases, alimony, child support, or long‑term disability income can be counted, again with the right paperwork and proof that it will continue.
If you are unsure whether a particular income stream “counts,” that is a perfect conversation to have with a lender. Often, buyers underestimate how much qualifying income they actually have once everything is properly documented.
Practical Mortgage Tips to Improve Your Qualification Odds
The great thing about the mortgage process is that you are not stuck where you are today. With a bit of planning, you can strengthen your application and make those income requirements easier to meet. Here are some friendly, actionable mortgage tips for California home buyers and the real estate professionals who guide them:
- Trim high‑interest debt: Paying down credit cards or personal loans can quickly lower your debt-to-income ratio and free up room for a higher mortgage payment, even if your income stays the same.
- Avoid new loans before applying: Financing a new car or taking out a big personal loan shortly before you apply can push your DTI too high. If possible, wait until after closing for major new obligations.
- Document every income source: Keep organized records—pay stubs, award letters, lease agreements, and tax returns—so your lender can capture every qualifying dollar of income.
- Consider a co‑borrower: In some cases, adding a spouse, partner, or family member with solid income and credit can help you qualify for a higher purchase price while still meeting the lender’s guidelines.
- Adjust expectations, not your dream: Starting with a slightly lower price point, different neighborhood, or townhome instead of a single‑family home can bring the numbers into reach without giving up on homeownership altogether.
Partner with a Mortgage Expert Who Knows California
Navigating income guidelines, loan options, and local price realities can feel overwhelming if you try to figure it all out alone. The encouraging news is that you do not have to. A trusted mortgage professional can review your full financial picture, explain your options in plain language, and help you design a clear, step‑by‑step plan to qualify—whether you are ready to buy now or in six to twelve months.
For California home buyers, that kind of local expertise is especially valuable. An experienced lender can:
- Estimate how much home you can comfortably afford based on your income and debts today.
- Suggest specific strategies to improve your debt-to-income ratio and strengthen your application.
- Match you with loan programs that fit your employment type, down payment, and long‑term goals.
Whether you are a first‑time buyer wondering where to start, or a real estate professional helping clients understand income requirements, connecting with a knowledgeable mortgage expert can turn a confusing process into a clear, confident plan. You deserve answers tailored to your situation, not just generic online calculators.
If homeownership in California is on your horizon, start the conversation now. Reach out to a trusted local lender, share your goals and your current numbers, and let them help you map out your next steps. With the right guidance, a smart strategy, and a clear understanding of how your income fits into the picture, qualifying for a mortgage can be much more achievable than it first appears.
SEO Title: How Much Income Do You Need to Qualify for a Mortgage in California?
SEO Description: Learn how lenders view income, understand the debt-to-income ratio, and see what California home buyers need to qualify for a mortgage. Get practical mortgage tips and discover which income types count toward approval.
SEO Keywords: mortgage qualification, income requirements, debt-to-income ratio, California home buyers, mortgage tips