How Long Does It Take to Get Approved for an FHA Loan?
Mortgages, FHA Loans, California Home Buying
How Long Does It Take to Get Approved for an FHA Loan?
If you’re buying a home in California with an FHA loan, you’re probably wondering, “How long is this going to take?” With solid preparation and a knowledgeable mortgage broker, your FHA loan approval time can be predictable, so you, your buyers, and your sellers can plan with confidence.
A Quick Overview of the FHA Loan Timeline in California
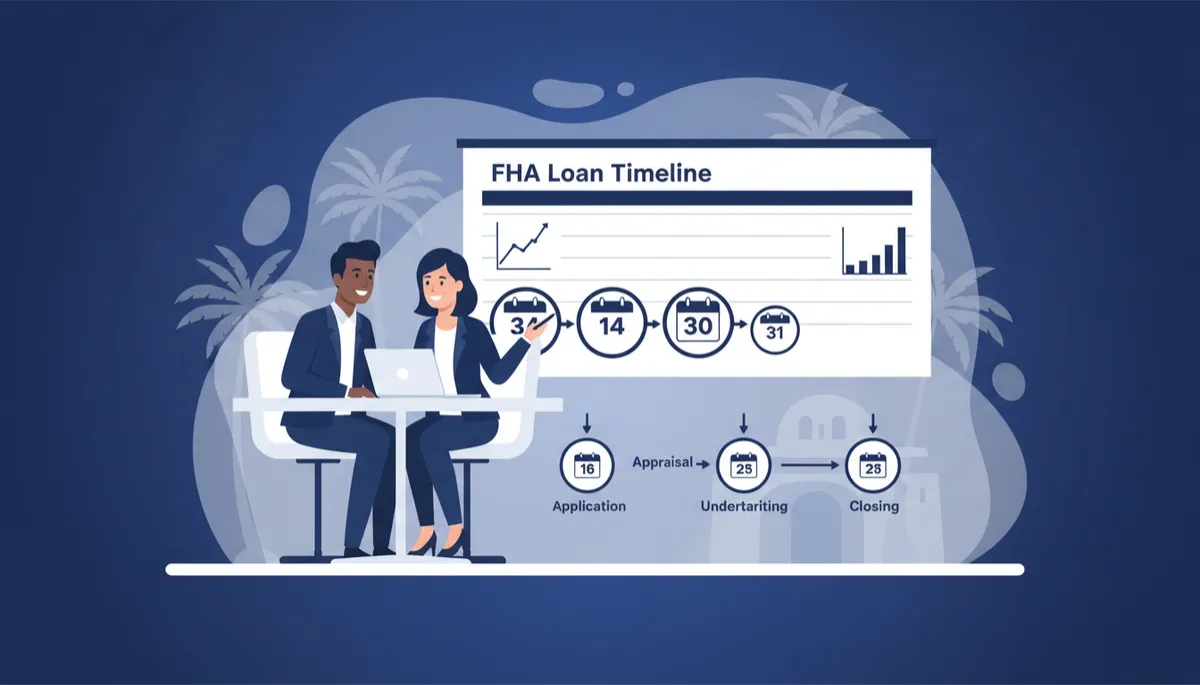
For most California buyers, the full FHA loan timeline runs between 30 and 45 days from accepted offer to closing. It helps to think of this in two main parts: FHA pre-approval (before you shop seriously) and full underwriting approval through clear-to-close (once you’re in escrow).
Pre-Approval vs. Full Approval: What’s the Difference?
1. FHA Pre-Approval (Usually 24–72 hours)
FHA pre-approval is your starting line. Kurt reviews your credit, income, assets, and debts to estimate how much you can borrow with an FHA loan California program, and with complete documents many buyers receive an FHA pre-approval within one to three business days.
A strong pre-approval letter gives you and your agent confidence when writing offers in competitive markets like Los Angeles, Orange County, the Bay Area, and San Diego, and shows sellers you’re a serious, qualified buyer even though you’re not fully approved yet.
2. Full Underwriting Approval to Clear-to-Close (Typically 25–40 days)
Once your offer is accepted, your file moves into full FHA underwriting, where the underwriter reviews your complete file, the property, and the appraisal to confirm everything meets FHA and lender guidelines. In a smooth transaction, full approval and clear-to-close usually land within a standard 30-day escrow, and sometimes faster with proactive coordination from everyone involved.
The Main Stages of the FHA Loan Process
- Initial conversation and FHA pre-approval – You connect with Kurt, share your goals and financial picture, and he checks current FHA county loan limits before issuing a pre-approval letter if everything lines up.
- Home shopping and offer – With your FHA price range and approval in hand, you and your agent shop for homes that fit your budget and FHA property guidelines, then write an offer supported by your pre-approval.
- File submission and initial underwriting – After acceptance, Kurt collects updated documents and the purchase contract, submits your file to underwriting, and the underwriter issues a conditional approval listing any items needed before final sign-off.
- Appraisal and property review – An FHA-approved appraiser confirms value and that the home meets FHA safety and livability standards, which is especially important for older, coastal, or unique California properties.
- Conditions and final approval – You, your agent, and Kurt work together to satisfy underwriting conditions, and once everything is cleared you receive a clear-to-close.
- Closing and keys – Loan documents are prepared, you sign, the loan funds, the deed records, and then it’s time to celebrate with keys in hand.
“Most delays are avoidable when everyone knows the steps and responds quickly.”
— Kurt Kessler, Mortgage Broker (NMLS #365130)
What Can Slow Down FHA Loan Approval Time?
Even with a clear FHA loan timeline, a few common issues can stretch things out, especially in busy California markets:
- Incomplete or outdated documentation – Missing pay stubs, bank statements, tax returns, or unexplained large deposits can stall underwriting until clarified.
- Appraisal delays – In high-demand areas, appraisers may be booked out, so slow scheduling can easily add several days to your FHA loan approval time.
- Property condition issues – Peeling paint, missing handrails, roof problems, or safety hazards can trigger repair requirements and re-inspections before the loan can close.
- Going over FHA county loan limits – If the price or loan amount exceeds your county’s FHA limit, you may need to restructure the deal or explore other loan options, which takes extra time.
- Last-minute credit changes – New debts, inquiries, or missed payments during escrow can force the underwriter to re-evaluate your approval and slow things down.
Tips to Speed Things Up for California FHA Buyers
A smooth FHA loan timeline starts well before you write an offer. Here are practical ways California buyers can help keep things moving quickly from pre-approval to clear-to-close:
- Get fully pre-approved early – Start the FHA pre-approval process with Kurt as soon as you’re serious about buying so any credit or documentation issues can be handled before you’re in escrow.
- Have your documents ready and in digital form – Two years of tax returns, W-2s, recent pay stubs, bank and retirement statements, and ID should be easy to upload, and quick responses to requests can shave days off your FHA loan approval time.
- Understand FHA appraisal and condition expectations – FHA wants homes that are safe, sound, and secure, so if you’re eyeing an older bungalow, fixer, or property with visible issues, talk with Kurt and your agent about potential repairs before writing the offer.
- Check FHA county loan limits early – Each California county has its own FHA loan limits, and Kurt will help you confirm your target price and down payment fit within the applicable FHA loan California limit.
- Avoid big financial moves during escrow – Hold off on new credit cards, car loans, or major purchases until after closing so underwriting doesn’t have to re-approve your file.
FHA Loan Timeline Tips for California Real Estate Agents
For agents, understanding the FHA loan timeline can make your offers stronger and your escrows smoother. Here are a few ways to partner effectively on FHA deals with your buyers and with Kurt:
- Set realistic escrow periods – With a well-prepared buyer and responsive parties, 30 days is often workable for FHA in California, but complex, rural, or repair-heavy properties may need a bit more time.
- Flag potential property issues early – If you see obvious safety or habitability concerns, loop Kurt in before writing the offer so the deal can be structured to avoid FHA appraisal surprises.
- Communicate with the listing side about FHA specifics – Many sellers are open to FHA buyers when they understand the process, especially if they know your buyer is fully pre-approved and working with a responsive local lender.
- Encourage fast responses on conditions – Help clients prioritize lender requests and coordinate needed documents from HOAs, employers, or escrow so conditions are cleared quickly.
Ready to Get Started? Connect with Kurt Kessler
The FHA loan approval time doesn’t have to be a mystery. With the right guidance, most California buyers can move from FHA pre-approval to clear-to-close on a predictable timeline that works for everyone in the transaction.
If you’re planning to purchase a home anywhere in California and want a clear, friendly walkthrough of your FHA loan timeline, reach out to Kurt Kessler, Mortgage Broker (NMLS #365130). Kurt will help you understand your numbers, review FHA county loan limits for your area, and map out a step-by-step plan from pre-approval to closing—so you can focus on finding the right home, not worrying about the process.
Ready to talk about your FHA loan in California? Contact Kurt today to get started on your pre-approval and put a realistic, confident timeline around your next move.