Calculate $800K Mortgage Payments in California
California Mortgages, Home Buying, Real Estate Finance
Calculate $800,000 Mortgage Payments in California
Wondering what an $800,000 mortgage really costs each month in California? You’re not alone. Between rising rates, property taxes, and homeowners insurance, it can feel like a lot to sort through. Let’s walk through the numbers together in plain English so you, your clients, or your buyers can plan with confidence.
What Does a Typical $800,000 Mortgage Payment Look Like Today?
As of mid‑October 2026, average California mortgage rates for a 30‑year fixed loan are hovering around 7.3%–7.4%, according to MonitorBankRates and HSH.com. That’s the broad market. Individual lenders, especially credit unions and experienced loan officers, may offer lower, more competitive rates depending on your profile.
To keep things simple, let’s use a **30‑year fixed rate of 7.35%** as a reasonable example for an $800,000 loan amount. We’ll assume this is the amount you’re borrowing (not the purchase price), and then layer in the other key costs you’ll see in a typical California payment:
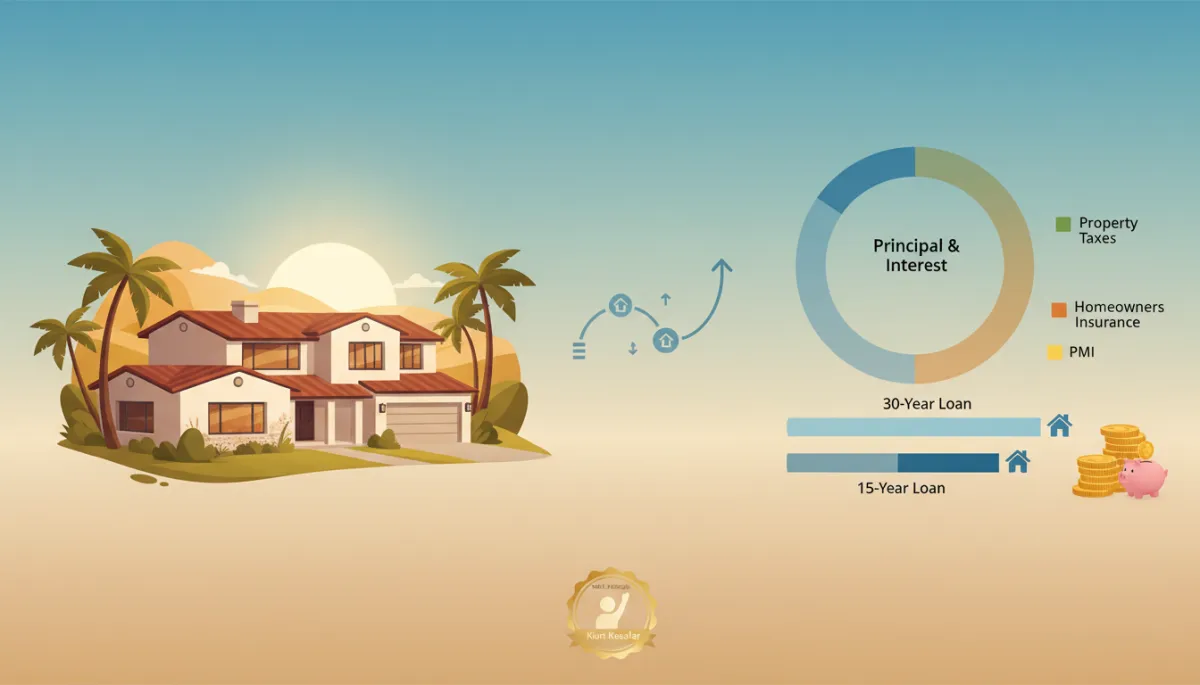
- Principal & Interest (P&I): the core mortgage payment that pays back the loan and interest to the lender.
- Property taxes: paid to your county and local districts, usually collected monthly through your mortgage servicer.
- Homeowners insurance: protects the structure and your belongings, required by most lenders.
- PMI (Private Mortgage Insurance): applies if you put less than 20% down on a conventional loan.
Sample 30‑Year Payment on an $800,000 Loan in California
Using a 30‑year fixed rate of 7.35%, the **principal & interest** payment on an $800,000 loan is roughly:
P&I ≈ $5,510 per month (rounded estimate).
Now let’s add the other pieces that matter in California:
- Property taxes: California’s average effective property tax rate is around 0.70% of market value, but new buyers in many areas should realistically plan on closer to 1.0%–1.2% once local assessments, bonds, and special districts are included. On an $800,000 home, that’s roughly $8,000–$9,600 per year, or about $670–$800 per month.
- Homeowners insurance: statewide averages are around $1,500–$1,600 per year for typical coverage, or about $125 per month, according to the California Department of Insurance and multiple national surveys. In wildfire‑prone or coastal brush areas, it can be much higher, so always price it out for the exact property.
- PMI (if less than 20% down): a rough planning number is 0.5%–1.0% of the loan amount per year. On an $800,000 loan, that could be around $330–$670 per month, depending on credit score and loan structure. PMI typically drops off once you build enough equity.
Put together for a buyer with less than 20% down, your **all‑in monthly payment** on an $800,000 loan could easily land in the neighborhood of:
$6,600–$7,100+ per month, depending on your exact tax rate, insurance costs, and PMI.
How Your Down Payment Changes the Monthly Payment
One of the biggest levers you control is your down payment. A larger down payment does two things:
- Lowers the amount you borrow (and therefore your P&I payment).
- Can help you avoid PMI if you reach at least 20% down on a conventional loan.
Let’s say the purchase price is $1,000,000 and you’re deciding between different down payment options:
- 20% down ($200,000): Loan amount = $800,000. No PMI on a standard conventional loan, and P&I is about $5,510/month at 7.35%.
- 10% down ($100,000): Loan amount = $900,000. P&I jumps to roughly $6,200/month at the same rate, plus you’ll likely have PMI on top of that until you build more equity.
- 5% down ($50,000): Loan amount = $950,000. Now P&I may be closer to $6,550/month, with a higher PMI cost because the lender is taking on more risk.
The takeaway: in California’s price range, an extra 5–10% down can make a meaningful difference in both monthly affordability and long‑term interest savings. However, many buyers still choose lower down payments to get into the market sooner—there’s no “one right answer,” just what fits your budget and timeline.
30‑Year vs 15‑Year Loan: Which Makes Sense for $800,000?
California’s average 15‑year fixed rate is currently around 6.9%–7.0%. That’s slightly lower than 30‑year rates, but the payments are spread over half the time, so the monthly amount is much higher even though you save a huge amount of interest overall.
- 30‑year fixed at 7.35% on $800,000: about $5,510/month in P&I.
- 15‑year fixed at 6.9% on $800,000: roughly $7,100–$7,200/month in P&I (ballpark).
With a 15‑year loan, you’ll:
- Build equity much faster.
- Pay significantly less total interest over the life of the loan.
- Take on a higher monthly commitment, which may limit flexibility for savings, travel, or investments.
Many California buyers choose the 30‑year option for breathing room, then make extra principal payments when their cash flow allows. A good loan officer can model side‑by‑side scenarios so you, or your clients, see exactly how each term affects monthly payments and long‑term costs.
How Property Tax Rates Vary by California County
California property taxes start with a 1% base rate under Proposition 13, but local voter‑approved measures and special districts add on top of that. That’s why a buyer in Kern County might see a different bill than someone in San Diego or Santa Clara, even at the same price point.
- Counties like Kern can have nominal rates around 1.24%.
- Coastal and Bay Area counties such as Los Angeles, Alameda, Santa Clara, San Francisco, and San Diego often land around 1.17%–1.22% when you include local bonds and assessments.
- Lower‑rate counties may be closer to the 1.00% base rate, especially in more rural areas.
For a new purchase at $800,000, it’s wise to assume a total effective rate between 1.0% and 1.25% unless you’ve checked the specific address. That means:
- At 1.0% → about $8,000/year or $667/month.
- At 1.25% → about $10,000/year or $833/month.
Real estate agents and loan officers in California often work together to estimate this early in the process, so there are no surprises when the first tax bill or escrow analysis arrives.
Tips for Qualifying and Comfortably Managing an $800,000 Mortgage
An $800,000 mortgage is a big commitment, but with a clear plan, it can absolutely be manageable. Here are some friendly, practical tips for buyers and the professionals guiding them:
- Know your true budget, not just what you qualify for. Lenders look at your debt‑to‑income ratio, but only you know how much room you want for savings, kids’ activities, or weekend trips to the coast. Build in cushion for life, not just the mortgage.
- Clean up your credit before you apply. Paying down revolving debt, correcting errors, and avoiding new credit inquiries can improve your score and potentially earn you a better rate, which has a big impact at this loan size.
- Plan for insurance and taxes by ZIP code. In California, two homes with the same price can have very different insurance and tax bills. Ask for property‑specific estimates, especially if the home is near canyons, brush, or wildfire‑prone areas.
- Consider a “payment you can sleep on.” If you qualify for an $800,000 loan but the payment feels tight, you might look at a slightly lower price point, adjust your down payment, or explore a 30‑year term with the option to pay extra when you’re comfortable.
- Build a simple reserve plan. Many California buyers feel more relaxed when they keep three to six months of mortgage payments in savings. It’s not always required, but it can make homeownership feel a lot less stressful.
Ready for Real Numbers? Talk with Kurt Kessler (NMLS #365130)
Online calculators and rough estimates are a great starting point, but they can’t see your full picture: your income, credit, location, property type, and goals. That’s where an experienced California loan professional makes all the difference—especially at an $800,000 loan level and above.
Kurt Kessler (NMLS #365130) works every day with California home buyers and real estate pros who need clear, honest answers about payments, closing costs, and what it really takes to qualify. He can:
- Run personalized payment scenarios for your exact price range and down payment.
- Compare 30‑year vs 15‑year terms, plus other options that might fit your plans.
- Help you understand how county‑specific taxes and insurance will affect your monthly payment.
Whether you’re a first‑time buyer trying to see if that dream home is within reach, or a seasoned agent wanting reliable numbers for your clients, you don’t have to guess. Reach out to Kurt Kessler (NMLS #365130) for a friendly, no‑pressure conversation and a customized quote based on today’s rates and your real‑world goals.
With the right guidance, an $800,000 mortgage in California becomes less of a mystery and more of a clear, manageable plan.