Calculate Payments on a $500k Mortgage in California
California Home Buying, Mortgage Guides
Calculate Payments on a $500k Mortgage in California
If you’re eyeing a $500,000 home in California, you’re not alone. Whether you’re a first-time buyer or a seasoned real estate professional helping clients, understanding the monthly mortgage payment on a 500k mortgage California is the key to confident decisions. Let’s break it down in friendly, plain English so you can see what’s realistic in today’s market.
What Really Goes Into Your Monthly Mortgage Payment?
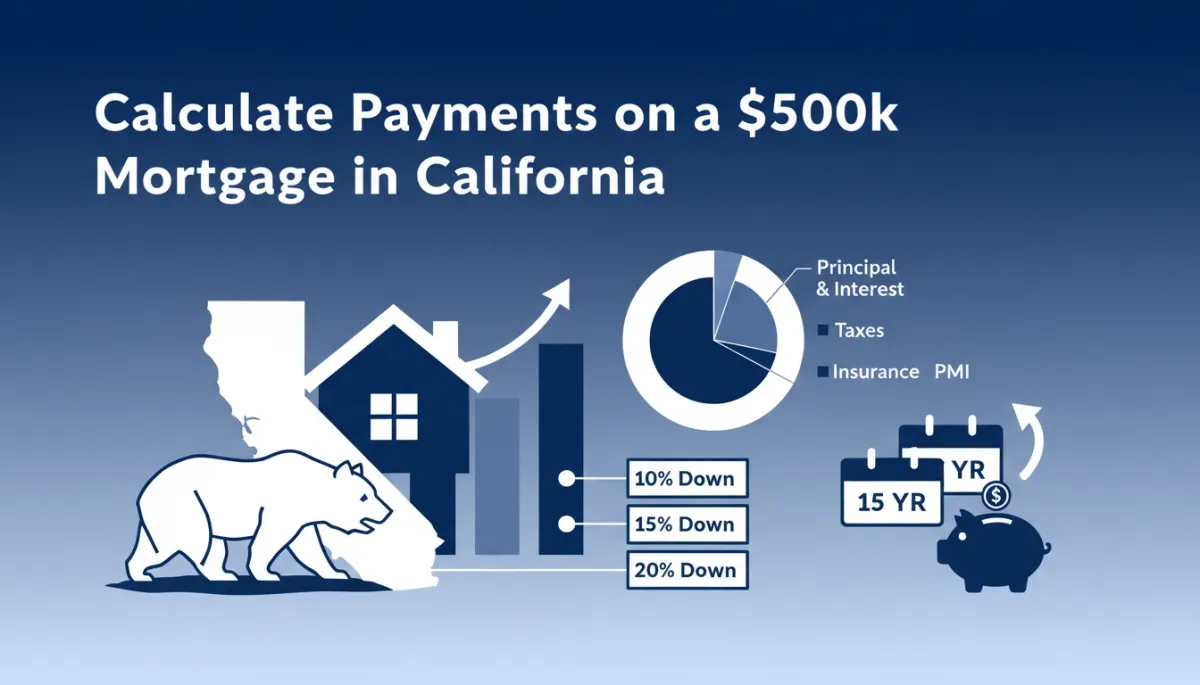
When buyers use a mortgage calculator, they often focus on principal and interest only. In California home buying, though, your monthly mortgage payment usually has five main pieces, often remembered as PITIA:
- Principal – The part of the payment that pays down the actual loan balance. On a $500k mortgage California scenario, this is the amount you’re slowly chipping away every month so you build equity over time.
- Interest – The cost of borrowing money from the lender. With 30-year fixed rates in California averaging around 7.1%–7.6% as of October 2026 (per Bankrate, Zillow, NerdWallet, and MonitorBankRates), this is a big slice of the payment early on.
- Taxes – Your property taxes, usually collected monthly and paid by your lender once or twice a year. Thanks to Proposition 13, California’s base rate is 1% of assessed value, with typical effective rates around 0.70%–0.72% of market value statewide. Many buyers can estimate roughly 0.7%–1.2% of the home price per year, depending on the county.
- Insurance – Homeowners insurance protects you and your lender. In California, averages run roughly $1,500–$1,700 per year for standard properties, or about $125–$150 per month, but wildfire-prone areas can be much higher, especially if a FAIR Plan is involved.
- PMI (Private Mortgage Insurance) – If your down payment is under 20% on a conventional loan, you’ll likely pay PMI. This protects the lender, not you, but it lets you buy with less cash down. It’s often in the range of 0.3%–1% of the loan per year, paid monthly, and can usually be removed once you reach about 20% equity.
Example Payments on a $500,000 Home: 10%, 15%, and 20% Down
Let’s put some real numbers to a 500k mortgage California scenario. We’ll assume a purchase price of $500,000 and a 30-year fixed rate at 7.5% (within the 7.1%–7.6% range many California buyers are seeing in October 2026). These are ballpark estimates, not quotes, but they’ll give you a realistic feel for where payments may land.
1. 10% Down Payment (with PMI)
Home price: $500,000
Down payment (10%): $50,000
Loan amount: $450,000
At 7.5% for 30 years, principal and interest land around $3,150 per month. Now add:
- Property taxes: Around 0.9%–1.1% of price annually in many counties. Using 1% as a simple estimate, that’s about $5,000 per year, or roughly $415/month.
- Homeowners insurance: We’ll use a mid-range estimate of $140/month.
- PMI: Suppose ~0.6% of the loan per year. On $450,000, that’s about $2,700/year, or roughly $225/month.
Estimated total monthly mortgage payment: about $3,930 (range roughly $3,800–$4,100 depending on exact taxes, insurance, and PMI).
2. 15% Down Payment (with Lower PMI)
Down payment (15%): $75,000
Loan amount: $425,000
Principal and interest at 7.5% for 30 years are about $2,975/month. Taxes and homeowners insurance are similar (they’re based on price, not loan size), so we’ll keep:
- Taxes: ≈ $415/month
- Insurance: ≈ $140/month
PMI is usually lower with 15% down, so let’s estimate around $150/month.
Estimated total monthly mortgage payment: about $3,680 (a reasonable range is $3,550–$3,850).
3. 20% Down Payment (No PMI)
Down payment (20%): $100,000
Loan amount: $400,000
At 7.5% for 30 years, principal and interest are roughly $2,800/month. Taxes and insurance stay close to:
- Taxes: ≈ $415/month
- Insurance: ≈ $140/month
With 20% down on a conventional loan, PMI usually disappears, which is a big monthly savings compared with 10% down.
Estimated total monthly mortgage payment: about $3,355 (roughly $3,250–$3,450 depending on county taxes and insurance).
How a 15-Year vs. 30-Year Loan Changes the Picture
Loan term is one of the biggest levers you have. California buyers often default to a 30-year term because it keeps the monthly mortgage payment lower. But 15-year loans can save a huge amount of interest over time, especially when rates are high.
30-Year Fixed on $400,000 (20% Down Example)
Using our earlier estimate at 7.5%, principal and interest are about $2,800/month. Over 30 years, you’ll pay a lot of interest, but your monthly cash flow is more manageable, which matters in higher-cost California markets.
15-Year Fixed on $400,000
Average 15-year rates are a bit lower—around 6.75% per Bankrate’s October 2026 data. On a 15-year term at 6.75%, the principal and interest payment jumps to roughly $3,550/month.
Taxes and insurance are the same, so your total payment could be closer to $4,100/month. The upside? You build equity incredibly fast and pay dramatically less interest over the life of the loan. For higher-income buyers or investors, this can be a smart play, especially if you want to enter retirement mortgage-free.
Practical Ways to Lower Your Monthly Mortgage Cost
Even in a higher-rate environment, you have options. Here are friendly, realistic strategies California home buyers and real estate pros can explore together:
- Boost your credit score. A stronger credit profile can move you from a 7.6% quote to something closer to the lower end of the range—or even into the 6% territory with certain credit unions, per MonitorBankRates. Over 30 years, that difference is huge.
- Shop aggressively for rates. Don’t just accept the first offer. Compare banks, mortgage brokers, and local credit unions. Rate spreads in California can be more than 1% between lenders on the same day.
- Consider a slightly larger down payment. Moving from 10% to 15% or 20% down can cut PMI or remove it entirely, reducing your monthly mortgage payment by $150–$250 or more.
- Ask about points and credits. Paying points upfront can buy down your interest rate; seller or builder credits can sometimes cover closing costs so you keep more cash for a larger down payment. A good lender can model both options in a mortgage calculator for you.
- Be strategic about location. In California, property taxes and insurance can swing widely by county and even by neighborhood. A home just outside a wildfire zone or in a slightly lower-tax county might save you hundreds per month without a big lifestyle trade-off.
- Plan to refinance later. Many buyers accept today’s payment knowing they can refinance if and when rates drop. It’s not guaranteed, but it’s a reasonable part of a long-term California home buying strategy.
Ready to Explore Your Own Numbers?
A $500,000 home in California can absolutely be within reach, even with today’s rates. The key is seeing the full picture—principal, interest, taxes, insurance, and PMI—and then tailoring the pieces so they fit your budget and your life.
If you’re a California buyer, start by plugging your own details into a trusted mortgage calculator and then talk with a local lender and real estate professional who understands your county’s property taxes, insurance realities, and available loan programs. Together, you can test different down payment California scenarios—10%, 15%, 20% and beyond—and compare 15- vs 30-year terms side by side.
Homeownership in California is still possible, and you don’t have to figure it out alone. Reach out to a knowledgeable agent or lender, run the numbers on your own 500k mortgage California scenario, and take the next step toward the front door of a home that truly fits you.